
Granite quarterly update
With bond yields rising in Q3, investors placed greater emphasis on earnings delivery over longer-term growth expectations.
What happened in the quarter?
Global markets faced a more complex backdrop in the third quarter (Q3) of 2026 as geopolitical tensions, renewed inflation concerns and changing monetary-policy expectations influenced performance across asset classes. Ongoing disruption in the Middle East and limited progress toward reopening the Strait of Hormuz kept energy prices elevated. This supported energy producers but increased cost pressures for transportation, industrial and consumer-oriented businesses.
Higher energy prices also contributed to a shift in interest rate policy. On September 16, the U.S. Federal Reserve raised its key interest rate by 25 basis points to a target range of 3.75%–4.00%, its first increase since 2023. Long-term government bond yields rose globally, including in Canada, creating a more challenging environment for fixed income and increasing valuation sensitivity for rate-sensitive equities.
Equities outperformed bonds over the quarter, supported by resilient earnings growth and investors’ continued risk appetite. Regional equity returns diverged, with U.S. equities outperforming on stronger earnings momentum and AI-related investments. Emerging markets and Japan also posted solid gains, while Europe lagged amid softer growth and weaker earnings trends.
Technology and AI-related companies continued to support market leadership through sustained investment and strong earnings expectations. Higher bond yields, however, increased differentiation between companies delivering current earnings and those relying more heavily on future growth expectations.
Canadian equity performance reflected its exposure to the financials, materials and energy sectors. Renewed U.S. tariffs and Canadian countermeasures weighed on industrials, exporters and companies with integrated North American supply chains. By quarter-end, relative performance among Canadian equities increasingly reflected their commodity exposure, earnings visibility, valuations, and sensitivity to interest rates and trade policy.
| Top contributors/detractors | |
|---|---|
+ Tactical positioning: The Granite Portfolios’ tactical overweight exposure to equities was a positive contributor to performance.
+ Manager selection was the main driver of performance, led by international equities, emerging markets, global mid-cap equities and high-yield fixed income.
+ Strategic allocation contributed positively, supported by positive equity market returns during the quarter. |
|
What changes did we make?
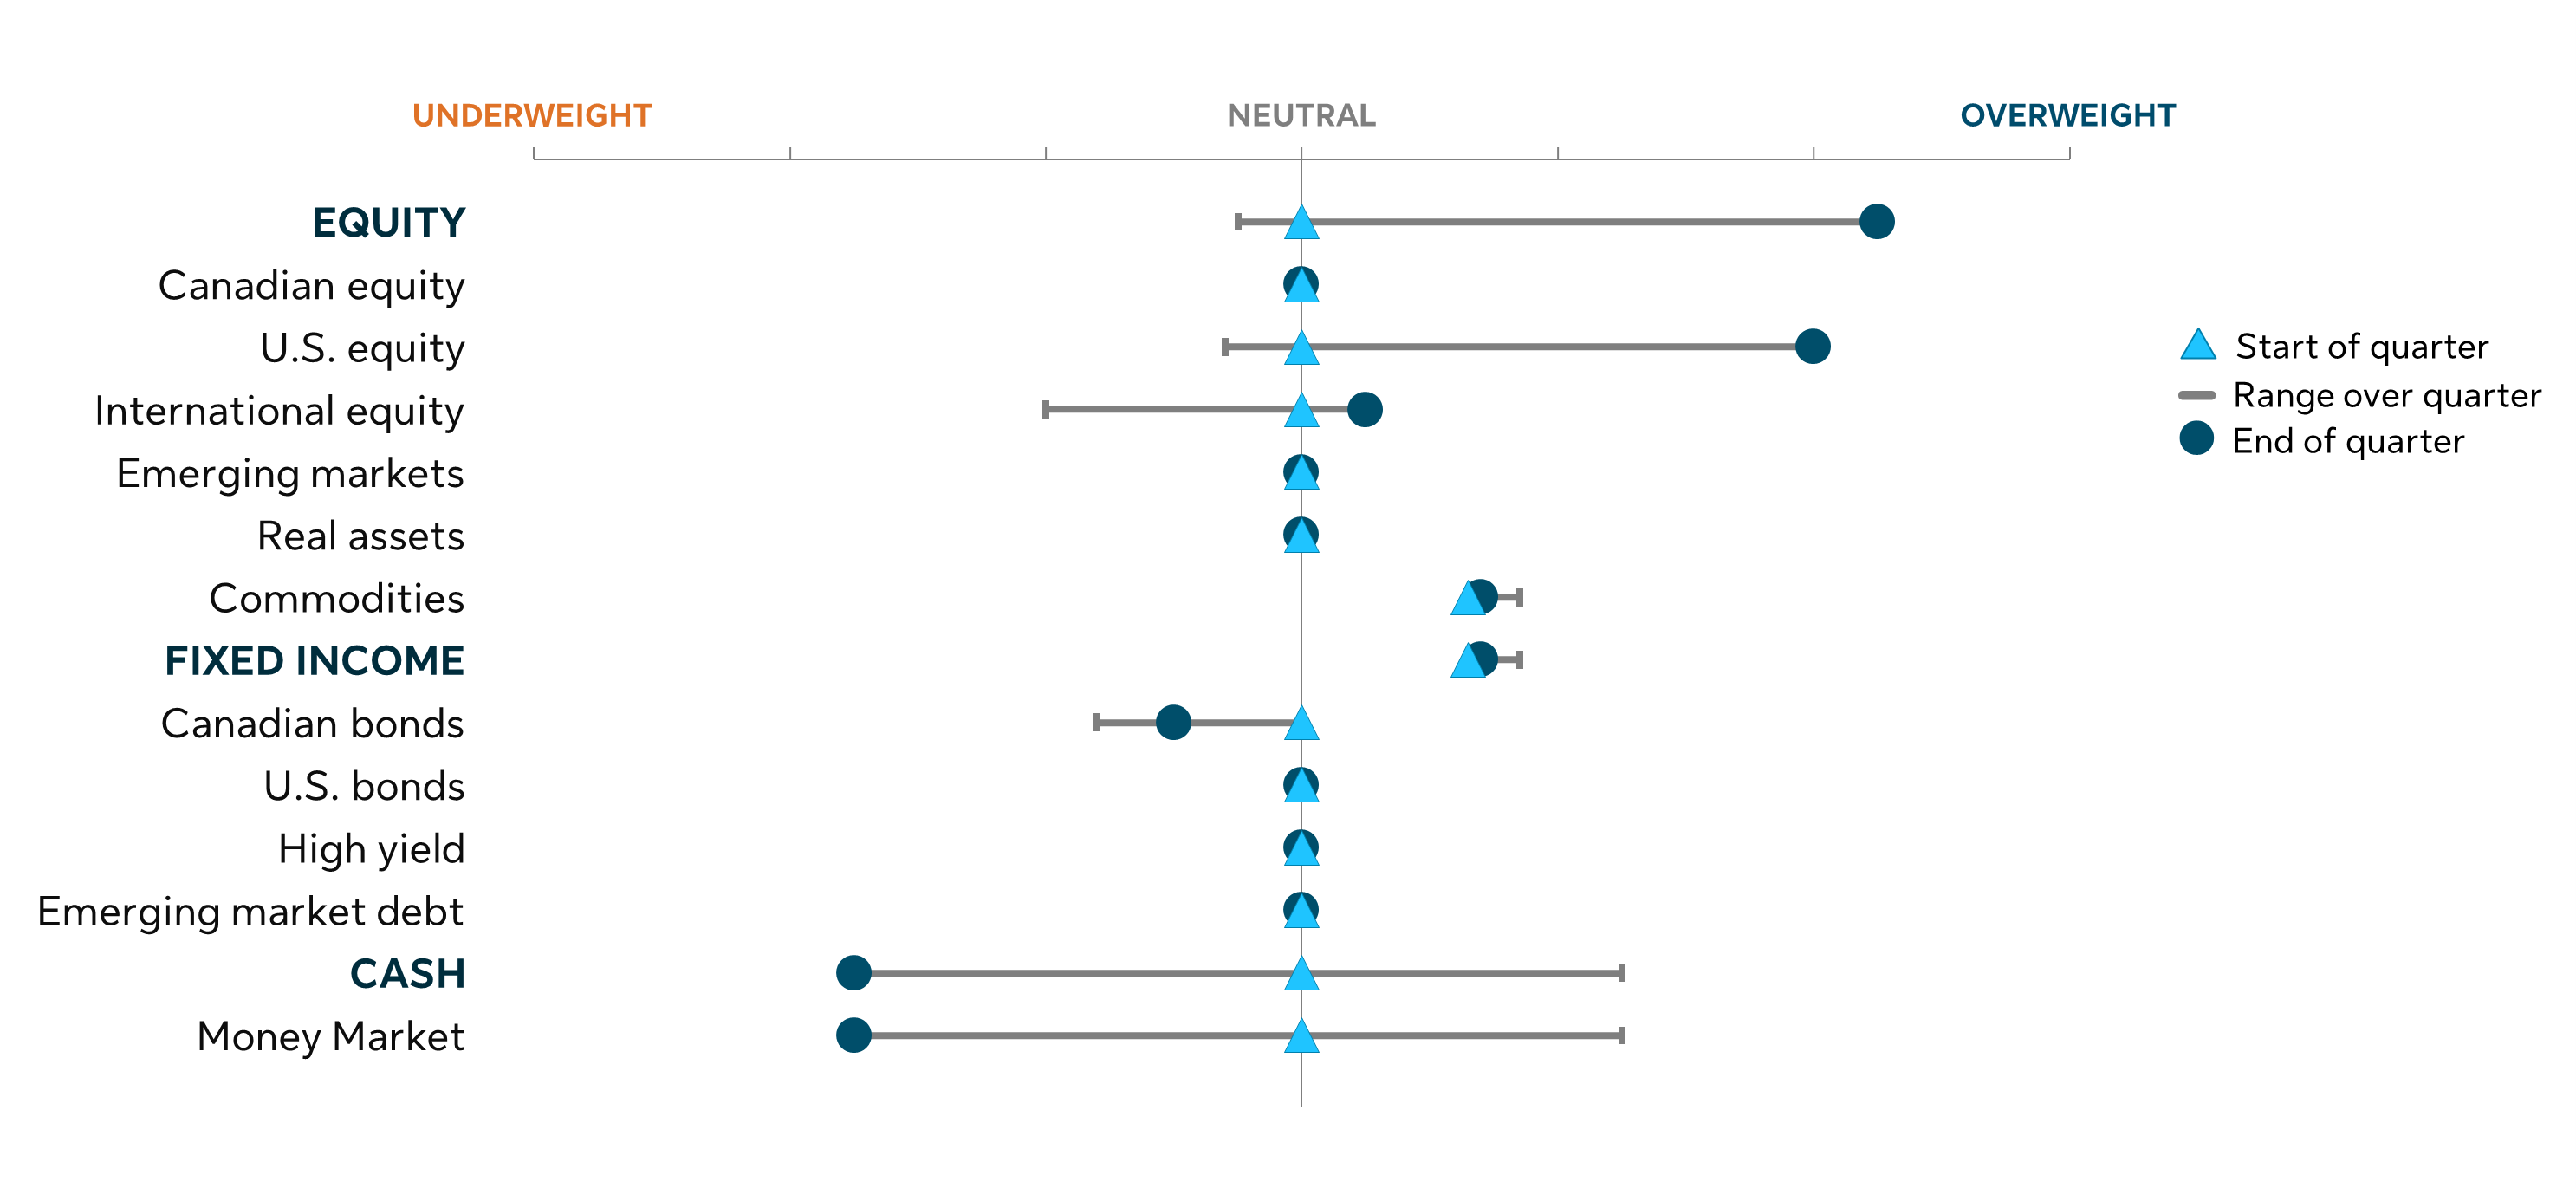
In Q3, we implemented two notable portfolio adjustments. Early in the quarter, we increased our strategic allocation to passive U.S. equities and exited active management within the asset class, increasing broad market exposure through index-based strategies.
Later in the quarter, we established a significant overweight position in U.S equities as market sentiment weakened amid inflation concerns and rising expectations for interest rate hikes. We also reintroduced a position in crude oil as global inventories remained low and supply conditions remained constrained.1 In addition to its standalone return potential, the crude oil position provides a partial hedge to our overweight U.S. equity exposure by increasing exposure to a different set of market drivers, in our view.
Q3 tactical asset class positioning
What’s next?
Heading into Q4 2026, markets face a mixed backdrop of resilient earnings, still-elevated valuations, steady economic activity and significant policy uncertainty. Our base case remains constructive, but more selective: we continue to favour equities, while emphasizing diversification across regions, sectors and investment styles rather than relying on further valuation expansion.
Corporate earnings remain supported by technology investment and generally stable economic activity. Market leadership broadened in July and August before narrowing again in September. With valuations above long-term averages, markets are increasingly sensitive to earnings expectations and economic data. Within equities, we favour companies with visible earnings, durable cash flows and credible returns on investment, particularly in AI.
Inflation has eased but remains influenced by energy prices, trade developments and geopolitical events, with higher energy costs potentially slowing progress toward central bank inflation targets. Against this backdrop, we expect monetary policy to remain restrictive, while long-term bond yields will likely continue to reflect inflation expectations, fiscal pressures and government borrowing needs. Although yields may remain volatile and haven’t necessarily peaked, in our view, higher starting yields have improved the return potential of high-quality bonds.
Overall, resilient earnings continue to support markets, but we believe future returns are likely to depend more on earnings delivery, valuation discipline and active portfolio positioning. We also believe that despite concentrated equity market leadership, earnings results continue to highlight a favourable demand-supply dynamics in AI. We enter Q4 with a moderate overweight to equities, reflecting a constructive earnings outlook while recognizing ongoing policy and valuation risks.
1 Indirect exposure to commodities is achieved by investing in underlying ETFs that seek to replicate the performance of the price of the broad commodity market.
Views expressed regarding a particular company, security, industry or market sector should not be considered an indication of trading intent of any mutual funds managed by SLGI Asset Management Inc. These views are subject to change and are not to be considered as investment advice nor should they be considered a recommendation to buy or sell. This commentary is provided for information purposes only and is not intended to provide specific individual financial, investment, tax or legal advice. Information contained in this commentary has been compiled from sources believed to be reliable, but no representation or warranty, express or implied, is made with respect to its timeliness or accuracy.
This commentary may contain forward-looking statements about the economy and markets, their future performance, strategies or prospects or events and are subject to uncertainties that could cause actual results to differ materially from those expressed or implied in such statements. Forward-looking statements are not guarantees of future performance and are speculative in nature and cannot be relied upon.